WARC has just published its report on advertising worldwide (link). The global advertising market is estimated at nearly $933 billion in 2024. 71% of investments are made in online media and 29% in traditional offline media.
The top media:
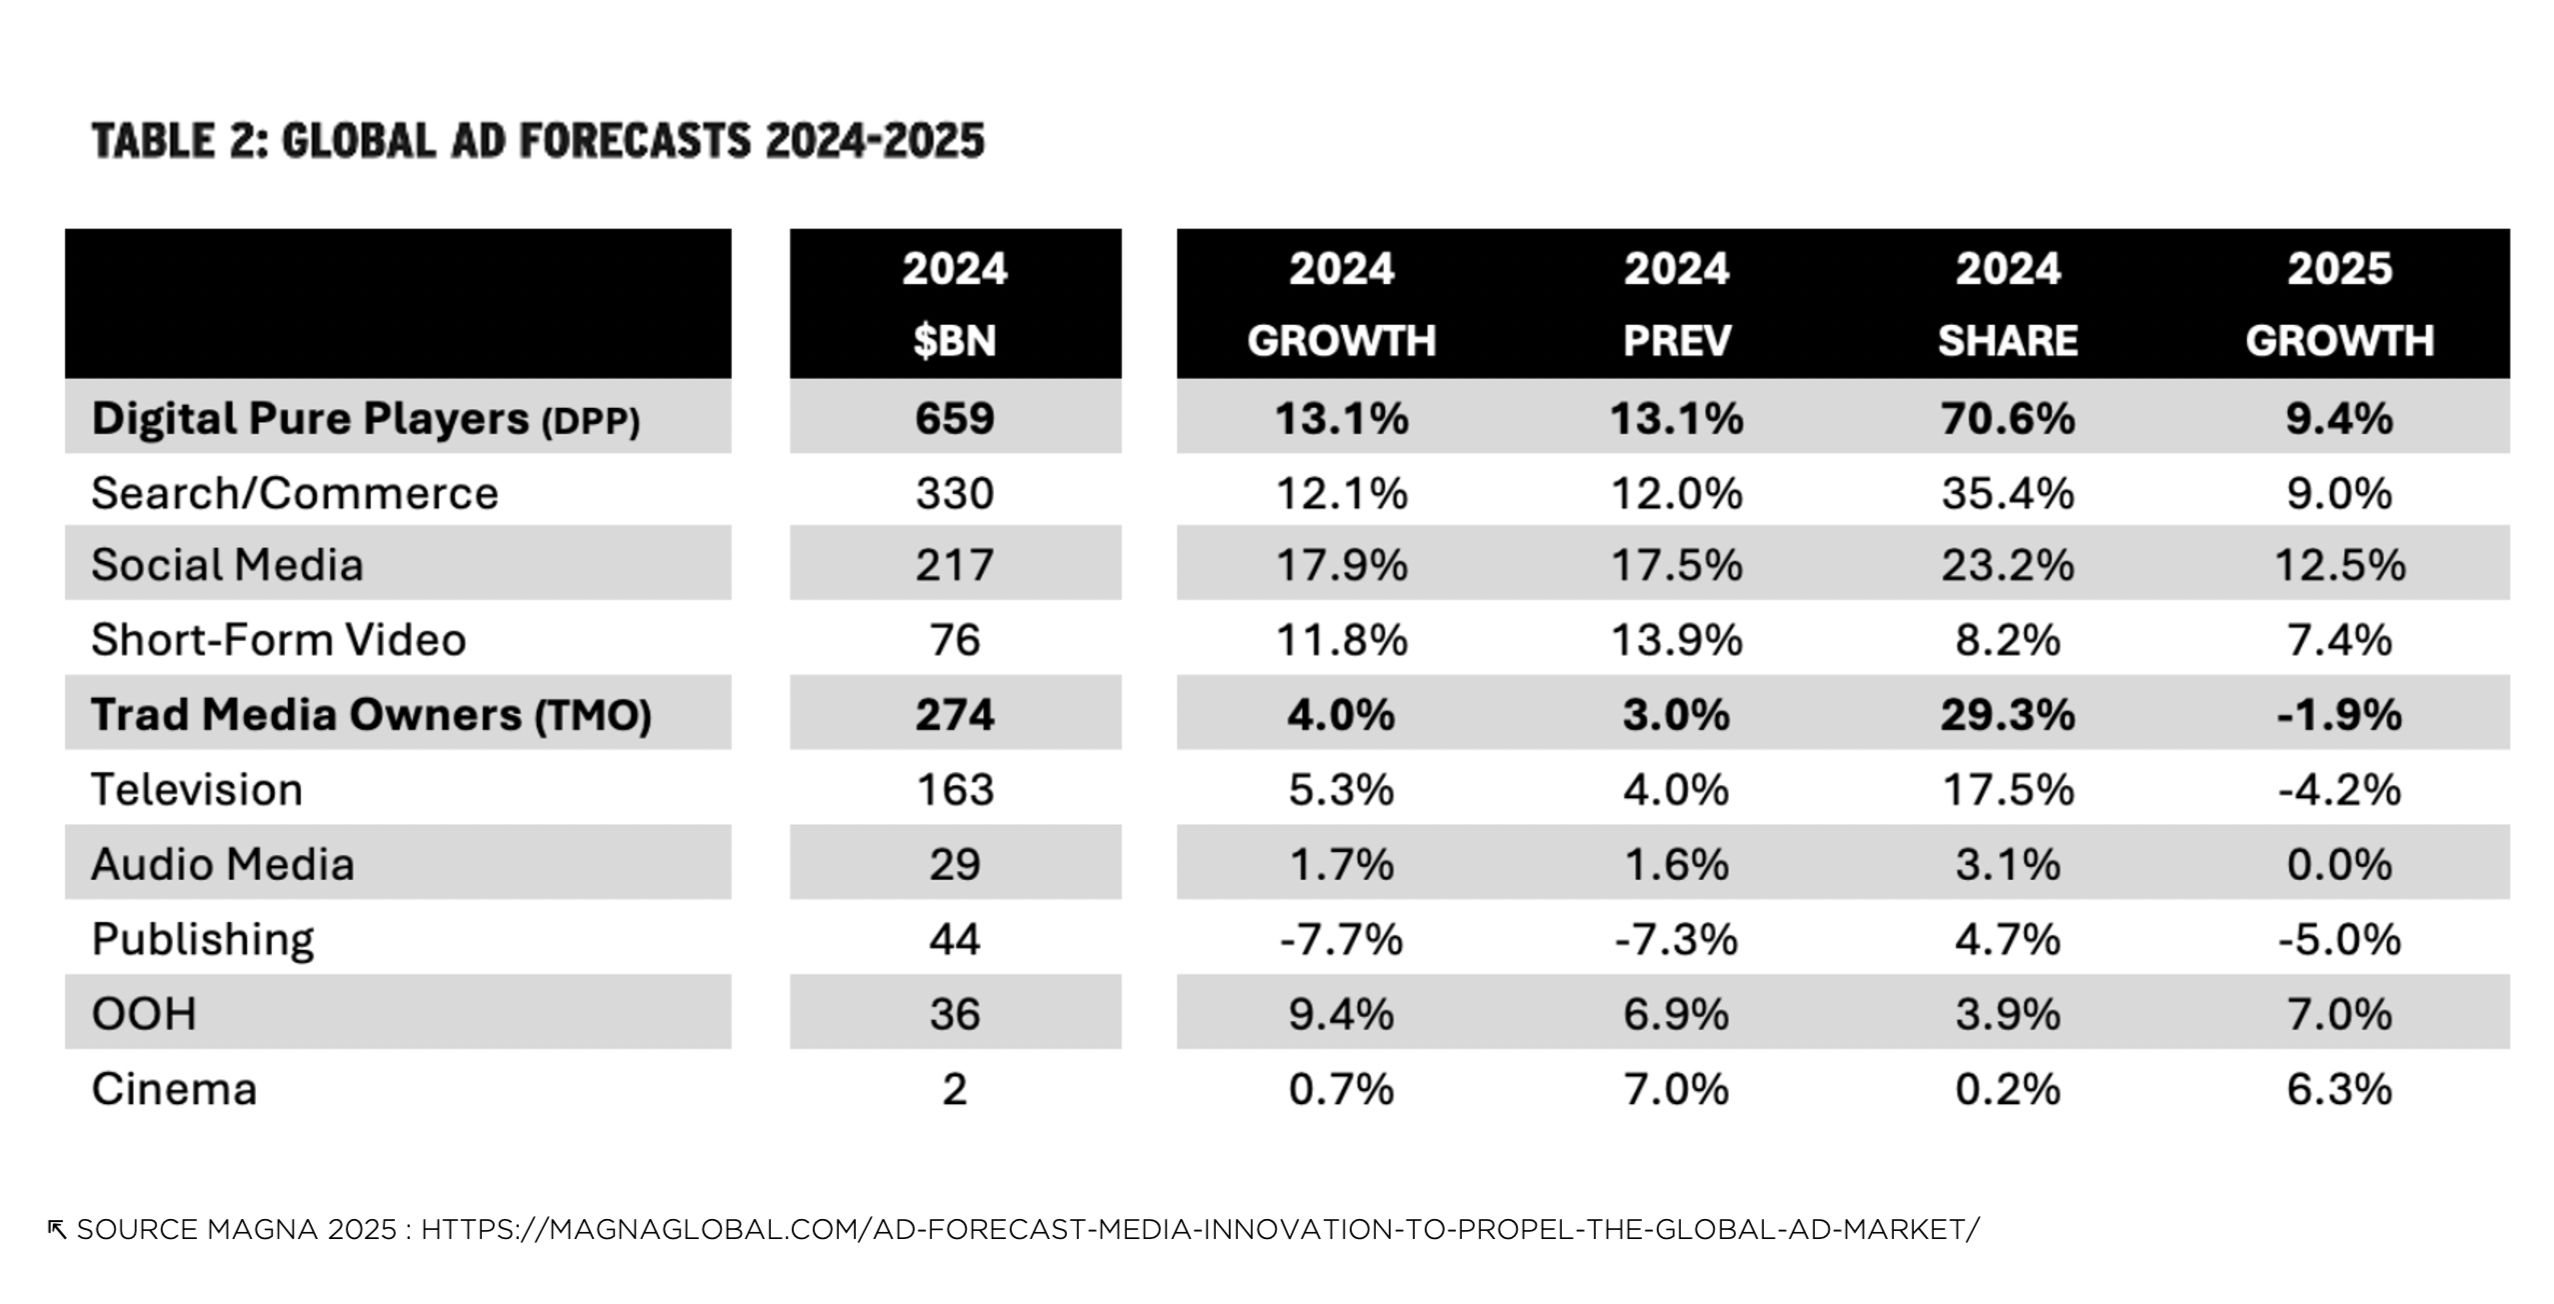
Paid Search dominates with $330 billion (35% market share – 1st place), followed by Paid Social with $217 billion (23% – 2nd place) and television with $163 billion (18% – 3rd place). It is worth noting that Paid Social has overtaken television as the main branding and performance lever for several years.
Differentiated growth between online and offline
The digital market shows average growth of +9.4%, while offline media decline by -1.9%. In digital, Paid Social outperforms with a rise of +18% in 2024, and expected growth of +12.5% in 2025.
On the offline side, only OOH (outdoor) is growing, with +7% in 2024 and a similar trend for 2025.
Among the most dynamic markets, WARC identifies the United States, the United Kingdom, India and France. France is expected to record growth of +12% on average, in line with the forecasts of the IREP / E-Pub Observatory / Udecam, which in fact observed growth of +13% in 2024.
Why this growth?
- A lasting consumption trend: Digital and, even more so, mobile have established themselves as unavoidable media, benefiting from growing screen time (up to more than 4h30 per day for the youngest audiences).
- More measurable platforms: The growth of SEA & SMA is mainly driven by advertisers’ ability to activate measurable levers, combining mass audience with sharp targeting on intent or behaviour. In addition, players’ efforts to address the challenges of a cookie-less world found a favourable echo on the Meta and Google platforms.
- A crowded offline environment: Offline media (excluding OOH / Cinema) attract ageing and less addressable audiences. However, their power, their status dimension and their impact on physical traffic keep them attractive, but this generates structural GRP inflation.
Opportunities for advertisers
- Brand Performance: It is possible to optimise online investments with an approach ensuring full performance measurement. You have to go beyond last click to measure the real impact of campaigns on conversion rate, price point, retail sales, etc.
- In-market shift: The increase in digital investments strengthens measurement and synergies between levers. Rather than sticking to a classic funnel, it is crucial to measure how to convert an out-of-market audience (not sensitive to the brand) into an in-market audience (category or brand intent). Proprietary solutions and tools provided by Meta, Google and other platforms make it possible to track this transformation.
- Content Performance: Content plays a major role in performance and impact. While offline media shorten the length of ad spots (20 seconds as the TV standard), thereby limiting storytelling, social networks today make it possible to build approaches combining short and long content, with perfectly controllable sequencing.
Paid Social and Search continue to dominate the global advertising landscape, offering advertisers unprecedented opportunities to maximise their impact and performance. In France, this dynamic confirms that the digitalisation of investments is more than a trend, it is a necessity.
Going further: our strategic consulting offer.
On the same topic: « Social growth in France: what drives it and how to read it? » and « TV and Social are neck and neck worldwide and in France: why, and what promises for 2022? ».
Keywords